Form 10-K for the fiscal year ended May 26, 2024
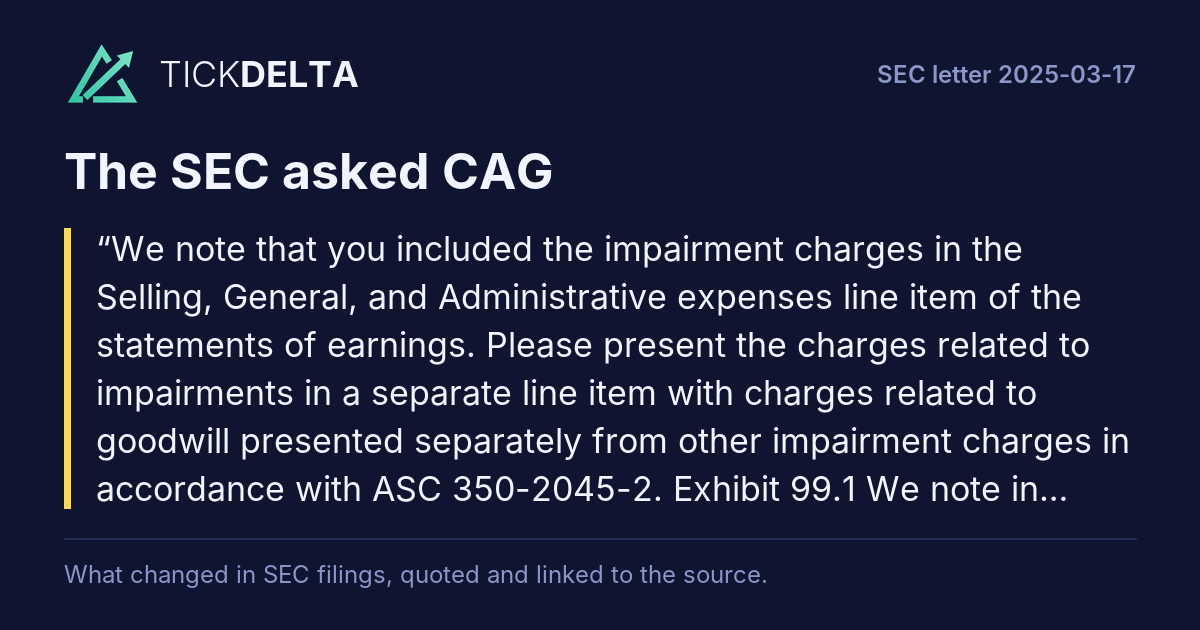
We note that you included the impairment charges in the Selling, General, and Administrative expenses line item of the statements of earnings. Please present the charges related to impairments in a separate line item with charges related to goodwill presented separately from other impairment charges in accordance with ASC 350-2045-2.Rest of the question
Exhibit 99.1 We note in your earnings releases, you removed advertising and promotion expenses from adjusted selling, general and administrative expense, a non-GAAP measure, because this metric is used in reporting to management, and management believes this adjusted measure provides useful supplemental information to assess the company’s 2. operating performance. Please tell us your consideration of the guidance in Questions 100.01 and 100.04 of the Compliance and Disclosure Interpretations on Non-GAAP Financial Measures. 3. We note your non-GAAP financial measures contain several reconciling adjustments. Please revise your discussion in your Note on Non-GAAP Financial Measures to further describe the nature of each adjustment and the reasons why management believes the adjustment and information is useful to investors. Refer to the guidance in Item 10(e)(1)(i)(C) of Regulation S-K.
In response to the Staff’s comment, in future filings, in the cost and expenses itemization in the statement of earnings, we will present charges related to impairments in a separate line item and we will separately present charges related to goodwill, if recognized. As disclosed in Note 8 – Goodwill and Other Identifiable Intangible Assets, we recognized goodwill and intangible impairment charges of $526.5 million and $430.2 million, respectively in fiscal year 2024.Read in the replyRest of the answer
We respectfully submit that the requested change would not materially change a reader’s understanding of the Company’s results of operations, as the nature and amount of the impairment charges is reflected within Note 8 and in our Critical Accounting Estimates.
First report after the company's reply of Mar 26, 2025: 10-Q filed Apr 3, 2025 ↗, against the 10-Q filed Dec 19, 2024 ↗.
Tickdelta does not hold the text of both reports, so they are not compared here.
Also in this review: closing letter, 2025-03-27